
How to Start Saving for a Home in Maryland Before You Are Ready to Buy
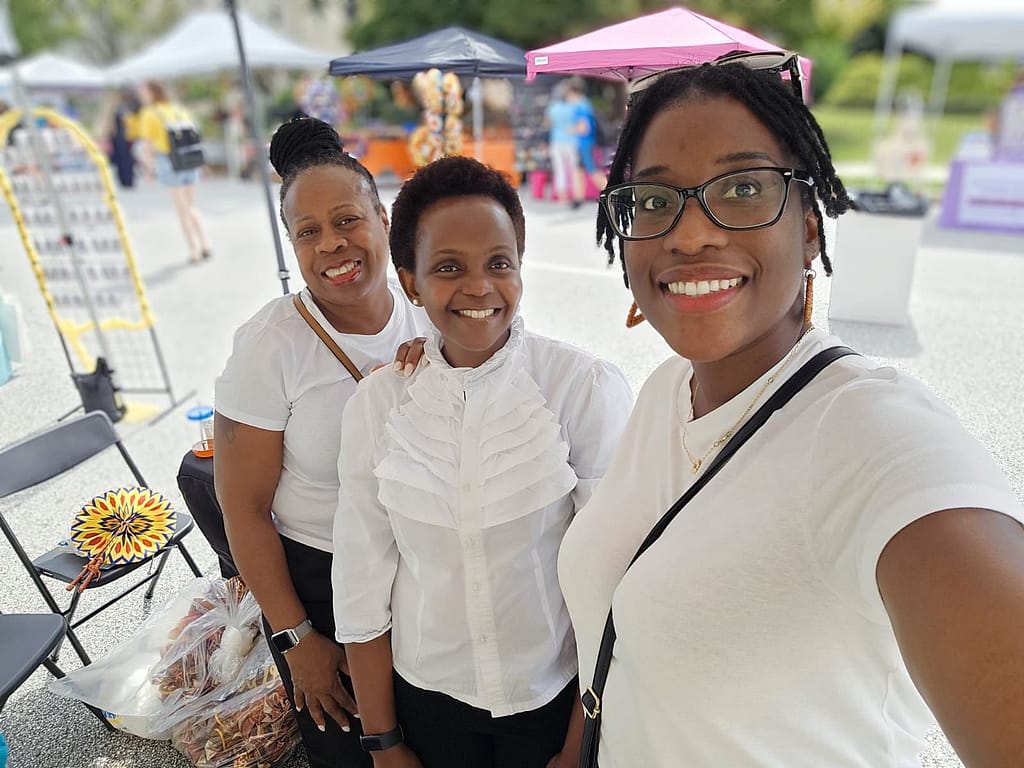
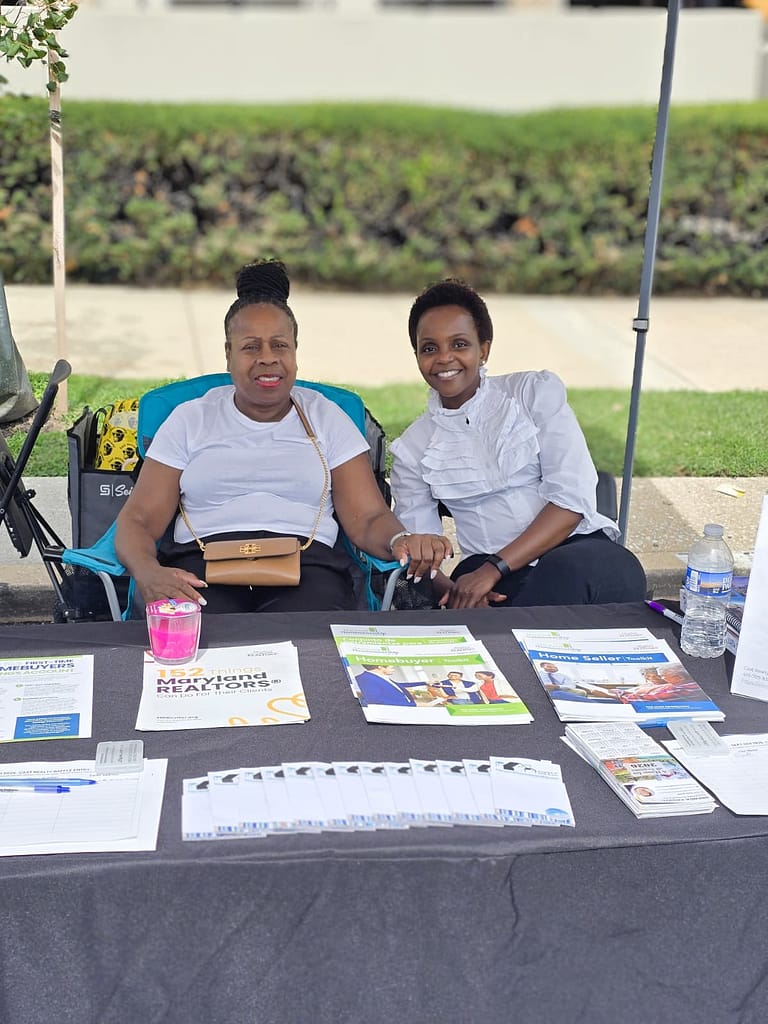
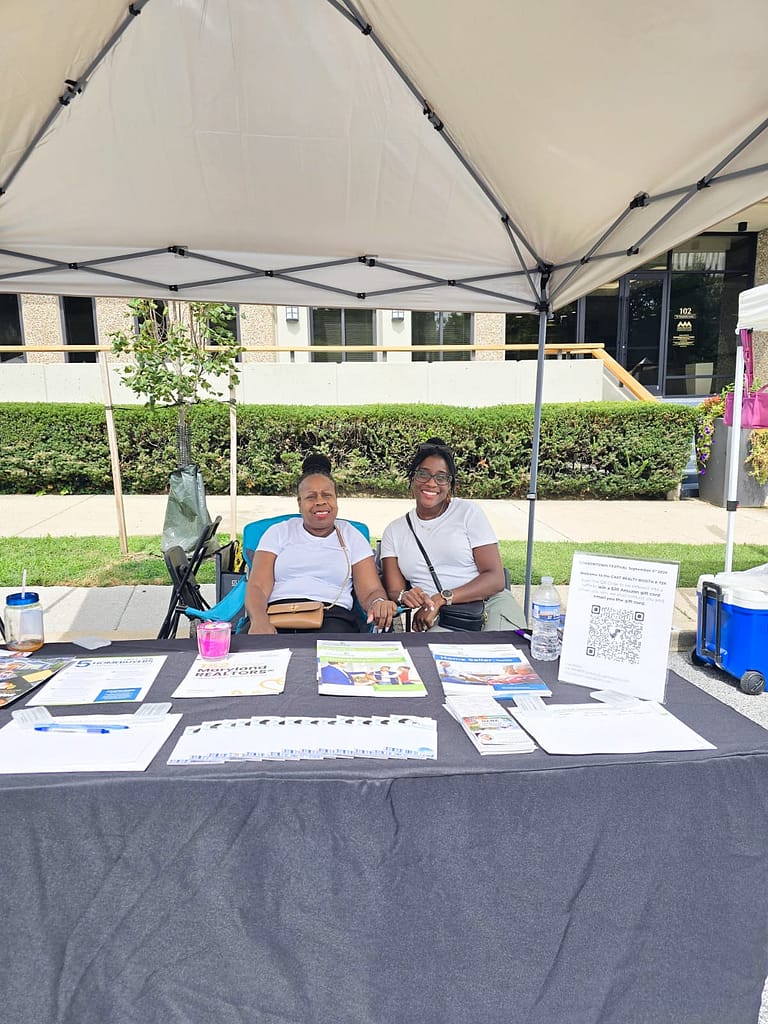
The weekend before Labor Day 2026, Cast Realty participated as a vendor at the Towson Fall Festival, hosted by the Towson Chamber of Commerce. Every community member we spoke with was unaware of Maryland’s First-Time Homebuyer Savings Account. Those conversations showed us how easily a valuable homebuying resource can go unused simply because people do not know it exists. That experience is one reason we are sharing this information: future Maryland homebuyers deserve to learn about the program early enough to include it in their savings plans.
Maryland offers a First-Time Homebuyer Savings Account benefit that may help eligible residents save for a future home purchase while claiming a subtraction on their Maryland income tax return. The earlier you learn how the program works, the easier it is to build it into your homebuying plan.
If you just renewed your lease, are still in college, or hope to buy a home in the next two to four years, this is a good time to start saving. You do not need to be ready for a mortgage today. You need a clear goal, a dedicated place for the money, and enough time for steady contributions to add up.
Cast Realty members – Brenda Kasuva (broker), Krystle Patrick and Rose Satterfield attended the Towson Fall Festival on Sept 5th 2026.
What the Maryland savings account benefit does
A First-Time Homebuyer Savings Account is a bank account you use solely to buy a home in Maryland. It does not have to be a special product offered under that name. An account at any financial institution may qualify if you use it only for your Maryland home purchase. Eligible account holders may claim the First-Time Homebuyer Savings Account subtraction on Maryland Form 502SU for up to 10 years. According to the Comptroller of Maryland, an account holder may subtract up to $5,000 contributed during the tax year, plus the account earnings for that year, subject to the program’s limits. This subtraction reduces Maryland taxable income; it is not a $5,000 tax credit or refund. An account holder may have only one qualifying account and must submit a list of the account’s transactions with the tax return for the year the subtraction is claimed and each following year until the funds are used for eligible costs. You must use the money within 15 years for the down payment or allowable closing costs on a Maryland home. Funds previously claimed as a subtraction that are withdrawn for another purpose generally become taxable as ordinary income and are subject to a 10% penalty, with limited exceptions. When the funds are used to purchase a home, the account holder must provide the Comptroller with financial institution statements and the settlement statement documenting how the money was applied.
Important: The $5,000 income subtraction is not the same as receiving a $5,000 tax refund or tax credit. The actual tax effect depends on your return. Review the current Maryland forms and speak with a qualified tax professional before claiming the benefit.
Who may qualify
Maryland Homeownership explains that you may be eligible to establish an account if you are a Maryland resident and have not owned a home in Maryland during the previous seven years. That definition means the program may apply to someone who has never purchased a home and, in some cases, to a person who owned a home in the more distant past. If two eligible buyers file a joint tax return, they may open a joint account.
Program rules and tax forms can change, so confirm your eligibility before opening or designating an account.
Five steps to use the account
- Confirm your eligibility: Review the current Maryland requirements, including residency and prior homeownership. If you plan to buy with another person, confirm how the rules apply to each account holder.
- Open a separate account: Ask your bank or credit union what account options are available. Keeping funds separate makes your contributions and account earnings easier to document.
- Contribute consistently: Set up an automatic transfer after each payday or once a month. You may also choose to add part of a bonus, tax refund, or financial gift. Family members cannot claim the account’s tax benefit, but you may add their gifts to your account.
- Keep records and claim the deduction: Track contributions and earnings, retain account statements, and use the current Maryland tax form. Make sure you receive Form 502SU, and track your contributions and interest earned.
- Use the funds for the Maryland purchase: The current program guidance gives the account holder up to 15 years after opening the account to use the money. Qualifying uses include the down payment and expenses or closing costs paid at settlement. Tell your mortgage lender and settlement provider that you plan to use funds from the account.
What steady saving can look like
A home savings goal becomes easier to manage when you turn it into a monthly number. The examples below show contributions only and do not include interest, investment gains, fees, or tax effects.
| Monthly amount | After 2 years | After 3 years | After 4 years |
| $250 | $6,000 | $9,000 | $12,000 |
| $400 | $9,600 | $14,400 | $19,200 |
| $600 | $14,400 | $21,600 | $28,800 |
Your target should reflect more than the down payment. A homebuying budget will include down payment, lender, title, and real estate agent fees, inspections, appraisal costs, moving expenses, initial repairs, and an emergency reserve. A lender and we at Cast Realty can help you estimate the amounts that fit your likely price range.
A plan for your current stage
If you recently renewed your lease, use the lease expiration date as your first planning deadline. Divide your savings goal by the number of months remaining, automate the contribution, and review your progress every three months.
If you are in college or early in your career, begin with an amount you can maintain. Even a smaller automatic transfer can establish the habit while you finish school, build income, and manage other obligations.
If buying is a two-to-four-year goal, work backward from a tentative purchase date. Review your credit, debt, expected income, and savings progress at least once a year. As the purchase date gets closer, speak with a lender about financing options and any homebuyer assistance programs that may be available at that time.
Watch our video
Want a quick explanation of the First-Time Homebuyer Savings Account? Watch the Cast Realty video on YouTube and learn how starting now can support your future Maryland home purchase.
Start your Maryland homebuying plan
You do not have to wait until you are ready for preapproval to start planning. Cast Realty can help you understand the homebuying process, set a realistic timeline, and identify the questions to discuss with a lender and tax professional. Visit CastRealtyMD.com to connect with our team and begin preparing for a future home purchase in Maryland.
Sources
1. Maryland Homeownership Home Buying Savings Account
2. Comptroller of Maryland 2025 Form 502SU
3. https://www.marylandcomptroller.gov/individuals/tax-services.html
4. Maryland Homeownership, 5 Steps to a First-Time Homebuyers Savings Account flyer, created August 2023.
